
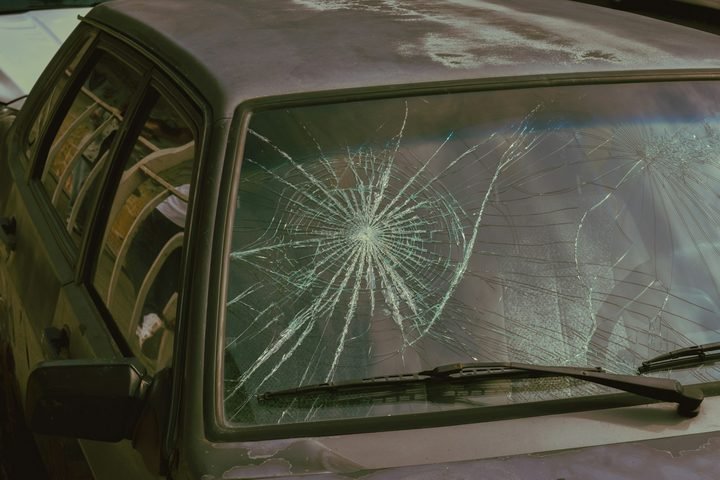
In 30 seconds
- Comprehensive coverage covers broken glass, such as windshield damage, according to the NAIC.
- If you carry only liability coverage, your insurer won't pay to fix your own windshield.
- Your comprehensive deductible usually applies, but some policies are sold so the deductible doesn't apply to glass.
- Florida law says the deductible doesn't apply to windshield damage on policies with comprehensive coverage.
In this article
Who pays for a cracked windshield?
- Liability only: you pay
- Comprehensive: covered, minus your deductible in most cases
- Glass coverage with no deductible: covered in full
- Florida, with comprehensive: no deductible on windshields
Based on the NAIC, NY DFS and Florida Statutes 627.7288.
Which part of your policy pays for a windshield
An auto policy is really a bundle of coverages, and only some of them pay for damage to your own car. The NAIC explains that comprehensive coverage pays for damage from almost all causes other than a collision, such as fire, severe weather, vandalism and theft, and it states plainly that comprehensive also covers broken glass, such as windshield damage.
| Coverage | Pays for your windshield? | Why |
|---|---|---|
| Liability | No | Liability pays for damage and injuries you cause to others, not your own car. |
| Collision | Sometimes | Collision pays when your car hits an object or another vehicle. If the windshield breaks in a crash, that claim may run through collision. |
| Comprehensive | Yes, in most cases | The NAIC says comprehensive covers broken glass, such as windshield damage. |
| Full glass coverage (where sold) | Yes, often with no deductible | New York's regulator notes coverage may be sold where the deductible doesn't apply to glass damage. |
Sources: NAIC, Auto insurance; NY DFS, Auto insurance information for consumers.
Not sure what you have? Your declarations page lists each coverage and its deductible. Our explainer on comprehensive vs collision coverage breaks down the difference.
Does the deductible apply?
In most states, a windshield claim works like any other comprehensive claim: the insurer pays the cost of the repair or replacement minus your comprehensive deductible. New York's Department of Financial Services lists common comprehensive and collision deductible options of $100, $200, $250, $500 and $1,000.
There are two big exceptions:
- ✓ No-deductible glass coverage. Some insurers sell comprehensive coverage where the deductible doesn't apply to window glass. You may see it called full glass or glass coverage. Check your policy wording.
- ✓ State law. Florida's statute 627.7288 says the deductible provisions of an auto policy with comprehensive coverage do not apply to damage to the windshield. If you have comprehensive in Florida, a covered windshield claim carries no deductible.
Rules differ by state. If you live outside Florida, ask your insurer or your state insurance department whether any glass deductible rule applies to you.
Claim it or pay yourself? Do the math first
A claim makes sense only if the payout is meaningfully bigger than your deductible. Get a written quote from a glass shop, then compare it with your deductible.
| Replacement quote | Your deductible | Insurer would pay | Worth claiming? |
|---|---|---|---|
| $350 | $500 | $0 | No. The cost is under your deductible. |
| $600 | $500 | $100 | Probably not. Small payout for a claim on your record. |
| $1,200 | $500 | $700 | Likely yes. |
| $1,200 | $0 (glass coverage or Florida) | $1,200 | Yes. |
Illustrative numbers only. Your quote, deductible and policy terms will differ.
Ask the shop for an itemized quote so you can see exactly what's included before you decide.
A real-life scenario
Marcus and the highway rock
Marcus has comprehensive coverage with a $500 deductible. A rock chips his windshield on the interstate, and within a week the chip spreads into a 10-inch crack.
He gets a written replacement quote of $1,150. Because that's well over his deductible, he files a comprehensive claim. His insurer pays $650 and Marcus pays the first $500.
His cousin in Florida has the same coverage. When her windshield cracks, she pays nothing out of pocket, because Florida law says the deductible doesn't apply to windshield damage on policies with comprehensive coverage.
Illustrative example. Names and numbers are made up to show how it works.
Chip repair or full replacement: questions to ask
Not every crack means a new windshield. A small chip caught early can sometimes be repaired, which is usually quicker and cheaper than replacing the whole glass. Whether your policy pays for a repair, and on what terms, depends on your insurer, so ask before work begins.
- ✓ Will you pay for a chip repair, and does my deductible apply to it?
- ✓ If I need a full replacement, how much will I pay out of pocket after my deductible?
- ✓ Can I choose my own glass shop, or do you work with specific shops?
- ✓ Will the shop bill you directly, or do I pay and get reimbursed?
- ✓ Will this claim affect my premium at renewal?
Write down the answers, the date and the name of the person you spoke with. Clear answers up front help you avoid surprise bills later.
How to file a windshield claim
- Take photos. Photograph the damage and note when and where it happened.
- Check your coverage. Confirm you have comprehensive coverage and look for any glass deductible terms.
- Get a quote. Ask a glass shop for a written, itemized estimate.
- Call your insurer or use its app. Report the damage and ask whether a chip repair or full replacement is covered, and how payment to the shop works.
- Keep your paperwork. Save the estimate, invoice and claim number until the claim is closed.
New York has an extra rule worth knowing if you live there: when you buy physical damage coverage, the insurer generally must inspect and photograph the vehicle, and a skipped required inspection can suspend that coverage until it's done. The same regulator says that after a physical damage claim is reported, the insurer must inspect the vehicle and make a good-faith offer within six business days.
Our step-by-step guide to filing an auto insurance claim covers what to expect after you report.
Should you add comprehensive or glass coverage?
Comprehensive is optional, so drivers with older cars sometimes drop it to save money. Before you do, think about how much a windshield, plus everything else comprehensive covers such as theft, hail and animal strikes, would cost you out of pocket.
- ✓ Ask your insurer what it charges to lower your comprehensive deductible or add glass coverage, and compare that with a likely replacement bill.
- ✓ Raising deductibles can lower your premium, as New York's regulator notes. Just make sure you could cover the deductible if something breaks.
See our guide to choosing an auto insurance deductible to find the right balance.
Frequently asked questions
Does auto insurance cover a cracked windshield?
Yes, if you have comprehensive coverage. The NAIC says comprehensive covers broken glass, such as windshield damage. Liability-only policies don't pay for your own car.
Do I have to pay a deductible for windshield replacement?
Usually your comprehensive deductible applies. Some policies are sold so the deductible doesn't apply to glass, and Florida law waives the deductible for windshield damage on policies with comprehensive coverage.
Is windshield replacement free in Florida?
If you have comprehensive coverage, Florida Statutes 627.7288 says the policy's deductible doesn't apply to damage to the windshield.
Is it worth filing a claim for a windshield?
Compare a written quote with your deductible. If the cost is close to or below the deductible, paying yourself may make more sense.
Does collision cover windshield damage?
If the windshield breaks in a crash, the claim may fall under collision. Damage from road debris, weather or vandalism is generally a comprehensive claim.
See what you could pay
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare auto insurance options
SponsoredRelated guides
See all auto insurance guides Comprehensive vs collision coverage: which one pays for what
 Picking an auto insurance deductible you can actually afford
 Just had an accident? How to file an auto insurance claim, step by step
 Hit a deer? What your auto insurance covers, and the steps to take right after
 Vehicle stolen? The steps to take with police and your auto insurance
 Buying a used car? How to spot hidden flood damage first
See auto insurance options near you
Rates and available coverages vary by state and insurer. Add your ZIP code to compare. It is free and you are not committing to anything.
Find auto insurance that fits your loan or lease
SponsoredSources
Disclaimer: This article is for general information only and is based on publicly available sources, which may be incomplete, outdated or incorrect. It is not legal, financial, insurance, tax or medical advice. ConnectingCrowd is not affiliated with any government agency, insurer or lender. Please do your own research and talk to a licensed professional before making any decision.