
Credit builder loans in four points
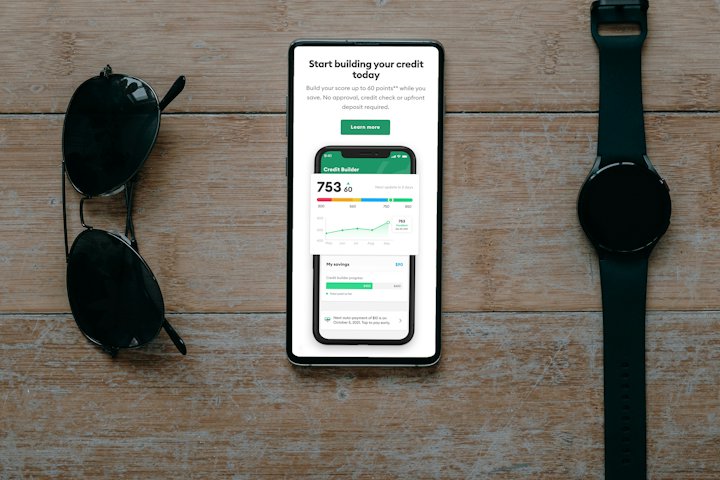
- With a credit builder loan, the lender holds the money while you repay it, the CFPB explains.
- Payments are typically small and run 6 to 24 months. Then you get the money you paid in.
- On-time payments are reported to credit bureaus and can help you build a credit history.
- CFPB research found these loans worked best for people who didn't already have debt.
In this article
Credit builder basics
- 6 to 24 monthsTypical repayment period
- HeldThe loan money stays in an account until you finish
- ReportedOn-time payments to the three nationwide credit bureaus
- Best fitPeople without existing debt, per CFPB research
From the CFPB.
How a credit builder loan works
The CFPB explains that you borrow from a bank or credit union, but the money isn't yours to spend right away. It is held in an account while you make small payments, typically over 6 to 24 months. When you finish, you get the money. In the CFPB's words, you build credit and savings at the same time.
- You apply at a bank or credit union that offers the loan.
- The money is set aside in an account you can't use yet.
- You make monthly payments, which are reported to credit bureaus.
- You get the funds once the loan is paid off.
Why it can help your credit
The CFPB says on-time payments on credit builder loans, secured cards and store cards are reported to the three nationwide credit reporting companies. Paying on time, every time, can help you build a strong credit history. Our guide on how loans affect your credit score explains more.
Who it helps most
A 2020 CFPB study found credit builder loans were more effective for people who entered the study without existing debt, both for establishing and improving credit scores. The CFPB also found the loan appeared to make it harder for some borrowers to keep up with their other loan payments. If money is already tight, an extra monthly payment could hurt more than it helps.
Ask about interest and fees before you sign. You will pay the loan back, but any interest or fees are a cost of building credit.
Other ways to build credit
| Option | How it works |
|---|---|
| Secured credit card | You put down a cash deposit, such as $500, and can spend up to that amount |
| Store or gas station card | Usually low limits, which makes it harder to run up big bills |
| Credit builder loan | Payments build credit while the money is held as savings |
From the CFPB.
What doesn't build credit
The CFPB says debit cards, cash and prepaid cards don't build credit history because no borrowing is involved. Payday loans don't help your credit history even if you pay on time. Some "buy here, pay here" auto dealers report only late payments, not on-time ones. See our guide to payday loans vs personal loans.
Is it right for you?
A credit builder loan may fit if you have little credit history, steady income and room in your budget for one more payment. If you already have debt you are struggling with, start with a budget or free credit counseling instead.
Frequently asked questions
What is a credit builder loan?
A loan where the lender holds the money in an account while you make payments. You get the money after it is paid off, and your payments are reported to credit bureaus.
How long does a credit builder loan take?
The CFPB says payments typically run 6 to 24 months.
Do credit builder loans really work?
CFPB research found they were more effective for people without existing debt. For some borrowers with other debts, the extra payment made it harder to keep up.
Where can I get a credit builder loan?
The CFPB says they are offered by banks and credit unions. Compare interest and fees before you apply.
Compare loan options for your situation
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare personal loan options
SponsoredKeep reading
Keep exploring personal loans
- Payday Loans vs Personal Loans: Costs and Safer Options
- Personal Loan Prepayment Penalty: Can You Pay Off Early?
- Buy Now, Pay Later vs a Personal Loan: Key Differences
- APR vs Interest Rate: Which Shows the Real Loan Cost?
- Debt-to-Income Ratio: How to Calculate DTI and Lower It
- Personal Loan Cosigner: Risks and Rules Before You Sign
- Personal Loan vs HELOC: Which Is Better for Your Project?
- Personal Loan Requirements: What Lenders Check First
- Personal Loan Origination Fees: The Real Cost Explained
Other topics:MedicareAuto insuranceLife insuranceHome insuranceDebt reliefAll guides
See loan options in your state
Loan options vary by state and lender. Enter your ZIP code to compare options. Looking is free.
Compare loan options for your situation
SponsoredSources
Disclaimer: Connecting Crowd is an independent information website. We do not represent any insurance company, lender, agency or government body. Everything on this site is for general information only. Details such as prices, rates and rules can change and may differ slightly from what is shown here, so please do your own research and verify any information with the official source or a qualified professional before making a decision. This page contains advertising, and we may be paid when you click a link or call a number.