
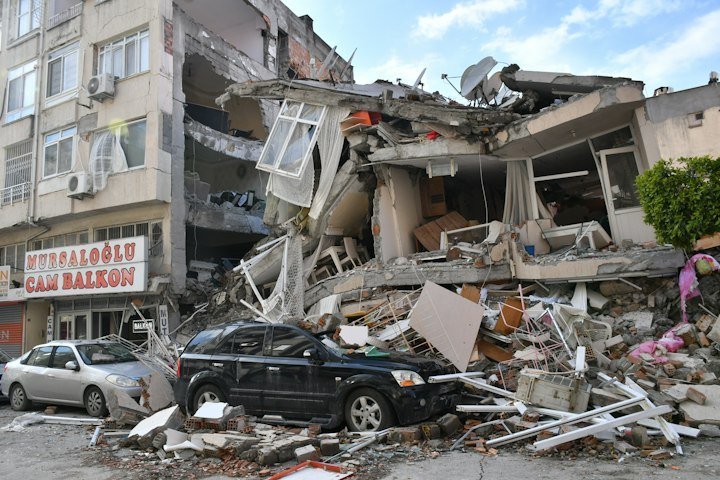
Earthquake coverage in four points
- Standard homeowners insurance does not cover earthquake damage. You add it by endorsement or buy a separate policy.
- Earthquake deductibles are a percentage of your coverage, often 10% to 15% or more, not a flat dollar amount.
- Fire and water damage from broken gas or water lines after a quake are generally handled by your homeowners policy.
- In California, the CEA offers deductibles from 5% to 25% and a discount of up to 25% for qualifying retrofitted older homes.
In this article
Numbers worth knowing
- 11%Share of U.S. homeowners with earthquake coverage, in an I.I.I. poll cited by the NAIC
- 2% to 20%Typical deductible range, per the NAIC
- 5% to 25%CEA deductible choices
- Up to 25%CEA discount for retrofitted pre-1980 homes
From the NAIC and the California Earthquake Authority.
What earthquake insurance covers
The NAIC explains that standard homeowners coverage does not include earthquake damage. Coverage is usually added as an endorsement to your policy or sold as a standalone policy.
| Type of damage | Which policy usually responds |
|---|---|
| Direct damage from the shaking | Earthquake policy or endorsement |
| Fire or water from broken gas or water pipes | Homeowners policy |
| Damage to your vehicle | Your auto policy |
Based on the NAIC's earthquake insurance overview. Check the wording of your own policies.
Why the deductible is so large
Most home deductibles are a set dollar amount. Earthquake deductibles are a percentage of the coverage limit. The NAIC cites a range of 2% to 20% of the insured value, and notes two separate deductibles of about 10% to 15% are common, one for the home and one for its contents.
A $500,000 home with a 15% deductible
The Chens insure their house for $500,000 with a 15% earthquake deductible. Their deductible is $75,000. A quake causes $60,000 of damage to the structure, so the policy pays nothing for that damage. A quake that causes $200,000 of damage would pay about $125,000.
Illustrative example. Some policies pay certain items, like emergency repairs, before the deductible.
California: the CEA policy
The California Earthquake Authority sells earthquake policies through participating insurers. For homeowners it offers these choices:
- Deductible: 5%, 10%, 15%, 20% or 25% of the dwelling limit. The 5% and 10% options are not available for homes with a dwelling limit over $1 million, or for certain older wood-frame homes without a verified retrofit.
- Personal property: $5,000 or $25,000.
- Loss of use: from $1,500 up to $100,000, with no deductible.
- Emergency repairs: no deductible on the first $1,500.
- Building code upgrades: $10,000 included, with $20,000 or $30,000 available.
The CEA's Hazard Reduction Discount can lower the premium by up to 25% for qualifying wood-frame homes built before 1980 that have been properly retrofitted.
Is earthquake insurance worth it?
- Check your risk. Earthquake risk is not limited to California. The NAIC's overview also tracks coverage in Washington State and the New Madrid region of the central U.S.
- Ask what you could cover yourself. Compare the deductible in dollars to your savings, and to the cost of rebuilding.
- Look at loss of use. Paying for somewhere to live while you rebuild can matter as much as repairs.
- Consider a retrofit. Bolting an older house to its foundation can lower risk, and in California can lower the premium.
- Get quotes for more than one deductible level.
Take-up is low, even in quake country
The NAIC cites an Insurance Information Institute poll finding only 11% of U.S. homeowners have earthquake coverage, and data showing about 10% of Californians do. In the New Madrid region of Missouri, coverage fell from 60.2% in 2000 to 11.4% in 2021. Many households would be paying for quake repairs from their own savings.
Frequently asked questions
Does homeowners insurance cover earthquakes?
No. The NAIC says standard homeowners coverage does not include earthquake damage. You need an endorsement or a separate earthquake policy.
How does an earthquake deductible work?
It is usually a percentage of your coverage limit, not a flat amount. On a home insured for $500,000 with a 15% deductible, you would pay the first $75,000 of covered damage.
Does earthquake insurance cover fire after a quake?
Fire and water damage from broken gas or water lines after an earthquake are generally covered by your homeowners policy, according to the NAIC.
See home insurance options for your situation
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare home insurance with earthquake coverage
SponsoredKeep reading
Other home insurance topics
- Condo Insurance: What the HOA Master Policy Leaves to You
- Sewer Backup Coverage: Why Home Insurance Often Excludes It
- Home Inventory for Insurance: A Room-by-Room Guide
- Hurricane Deductibles: How Percentage Deductibles Work
- Home Warranty vs Homeowners Insurance: What Each One Covers
- Umbrella Insurance: Extra Liability Beyond Home and Auto
- Does Homeowners Insurance Cover Roof Damage? When It Pays
- Does Homeowners Insurance Cover Water Damage? Key Rules
- What Does Renters Insurance Cover? Gaps Your Landlord Leaves
Other topics:MedicareAuto insurancePersonal loansLife insuranceDebt reliefAll guides
See home insurance options in your area
Earthquake coverage options vary by state. Enter your ZIP code to see what is available. Looking is free.
See home insurance options for your situation
SponsoredSources
Disclaimer: Connecting Crowd is an independent information website. We do not represent any insurance company, lender, agency or government body. Everything on this site is for general information only. Details such as prices, rates and rules can change and may differ slightly from what is shown here, so please do your own research and verify any information with the official source or a qualified professional before making a decision. This page contains advertising, and we may be paid when you click a link or call a number.