
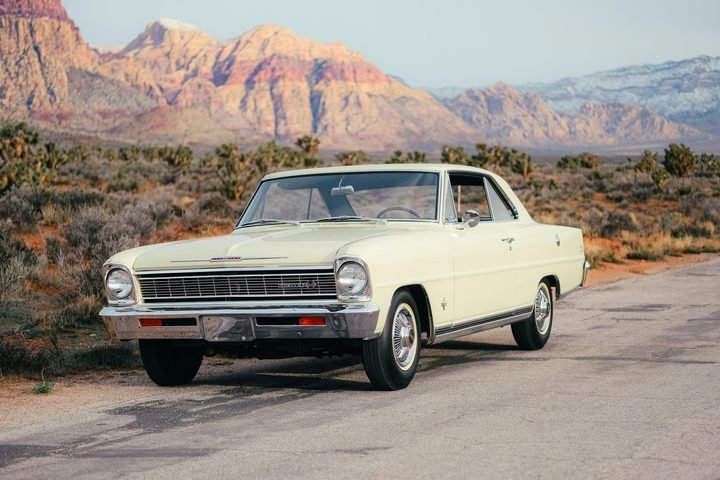
In 30 seconds
- Classic car policies usually cover the car for an agreed value that you and the insurer set, without depreciation.
- The car generally can't be used for everyday commuting or errands, and policies may limit mileage.
- Insurers usually require the car to be stored in a locked, enclosed, private structure like a garage.
- Cars are usually at least 25 to 30 years old, but Triple-I says age alone isn't enough to qualify.
In this article
Classic auto insurance at a glance
- Value: agreed value set in the policy, no depreciation
- Use: no everyday commuting or errands
- Mileage: may be limited
- Storage: locked, enclosed, private structure
- Age: usually at least 25 to 30 years old
- Spare parts: coverage worth considering
From Triple-I, Insuring your classic car. Insurers set their own rules and limits.
Why a regular policy may not fit
Standard auto insurance usually pays for a vehicle based on its value after depreciation. That works for everyday cars that lose value over time. But a classic car may hold its value or even appreciate, and there's often no standard book value to go by.
Triple-I explains that because there's no standard book value for many classics, the owner and the insurer agree on a value, which is specified in the policy. If the car is totaled or stolen, it's covered up to that value without depreciation.
| Standard auto policy | Classic car policy | |
|---|---|---|
| How the car is valued | Usually after depreciation | An agreed value set in the policy |
| How you can use it | Daily driving | Limited use; no everyday commuting or errands |
| Mileage | Usually no limit | May be limited |
| Storage | Usually no requirement | Locked, enclosed, private structure |
Based on Triple-I. Individual policies vary.
Setting the agreed value
The agreed value is the heart of a classic car policy, so it's worth getting right. You and the insurer agree on what the car is worth, and that amount is written into the policy. Triple-I suggests raising your coverage as the car gains value, so you're not underinsured after a restoration or as the market for your model rises.
Keep photos, restoration receipts and any appraisals. They help support the value you ask for and can speed up a claim.
Usage and mileage rules
Classic auto insurance policies come with rules about how the car is used. Triple-I says the car cannot be used for everyday commuting or errands, and policies may include mileage limitations. Some insurers also require you to have a separate vehicle for daily use.
Car shows, parades and club events are usually allowed, though Triple-I notes that some insurers limit those too. Read your policy's usage section so you know exactly where and how often you can drive.
- ✓ No daily driving. Commuting and errands are generally off limits.
- ✓ Watch your miles if your policy sets a limit.
- ✓ Have another car for everyday use if your insurer requires it.
- ✓ Check event rules for shows, club drives and parades.
Storage requirements
Where you keep the car matters. Triple-I says a classic car generally must be stored in a locked, enclosed, private structure, such as a garage or storage unit. A carport or driveway usually won't meet the requirement. If you move or change where the car is stored, tell your insurer.
Does your car qualify?
Not every old car counts as a classic for insurance purposes. Triple-I says classics are usually at least 25 to 30 years old, but a car's age is not enough to qualify. Insurers also look at the car's condition and the owner's record.
- ✓ Age: usually at least 25 to 30 years old.
- ✓ Condition: insurers may decline cars in poor condition or with prior damage.
- ✓ Driving record: insurers usually want a clean record.
- ✓ Use: the car must be a collector vehicle, not a daily driver.
Some insurers also cover newer collectible or exotic cars, so ask even if your car is younger than 25.
Don't forget spare parts
Parts for older cars can be rare and expensive. Triple-I suggests that coverage for spare parts should match the cost of replacing valuable and perhaps hard-to-find vehicle components. If you keep a stash of original parts in your garage, ask whether your policy covers them and up to what amount.
An example
Ruth's restored convertible
Ruth spends two years restoring a 1967 convertible. Her standard policy would pay only a depreciated value if it were totaled.
She switches to a classic car policy. She and the insurer agree on a value based on her receipts and an appraisal.
The policy limits her to a set number of miles a year and requires the car to be kept in her locked garage. She drives a newer car every day.
After the car wins a regional show and similar models rise in price, she asks the insurer to raise the agreed value.
Illustrative example. Names are made up.
How to shop for classic auto insurance
- Check eligibility Confirm the car's age, condition and your driving record meet the insurer's rules.
- Document the value Gather photos, receipts and appraisals.
- Agree on a value Make sure the agreed value is written into the policy.
- Read the usage rules Know the mileage limits and allowed events.
- Review it yearly Raise the value as the car appreciates.
Classic auto insurance vs. a standard policy
If you drive your older car every day, a classic policy probably isn't the right fit, because of the usage rules. A standard auto insurance policy may be a better match, even though it may value the car after depreciation. If the car is truly a collector vehicle that you drive occasionally and keep garaged, a classic policy's agreed value can offer better protection.
Either way, you still need liability coverage that meets your state's requirements. Ask the insurer what liability limits are available on a classic policy and whether they match what you carry on your other vehicles.
Frequently asked questions
Can I insure a car that isn't fully restored?
Possibly. Triple-I notes insurers may decline cars in poor condition or with prior damage, so ask how the insurer handles project cars.
Should I raise the agreed value over time?
Yes, if the car gains value. Triple-I suggests increasing coverage as the car appreciates.
What is agreed value coverage?
It's coverage where you and the insurer agree on the car's value up front. Triple-I says the car is covered up to that value without depreciation.
Can I drive my classic car every day?
Usually not. Triple-I says classic cars generally can't be used for everyday commuting or errands, and policies may limit mileage.
How old does a car have to be for classic auto insurance?
Usually at least 25 to 30 years old, but Triple-I notes that age alone isn't enough to qualify.
Where do I have to keep a classic car?
Triple-I says it generally must be stored in a locked, enclosed, private structure, like a garage or storage unit.
Do I need another car to get classic auto insurance?
Some insurers require you to have a separate vehicle for everyday use.
Are spare parts covered?
Some policies cover spare parts. Triple-I suggests coverage that matches the cost of replacing valuable, hard-to-find parts.
See what you could pay
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare auto insurance options
SponsoredRelated guides
See all auto insurance guides Comprehensive vs collision coverage: which one pays for what
 Vehicle totaled? How a total loss claim works, and how to push back on a low offer
 Auto insurance coverage types, explained with one bad day
 Staged auto accident scams: how the schemes work and how to protect yourself
 Catalytic converter theft: what auto insurance covers and how to protect your vehicle
 Auto insurance for college students: how to keep coverage and cut the cost
See auto insurance options near you
Rates and available coverages vary by state and insurer. Add your ZIP code to compare. It is free and you are not committing to anything.
Find auto insurance that fits your loan or lease
SponsoredDisclaimer: This article is for general information only and is based on publicly available sources, which may be incomplete, outdated or incorrect. It is not legal, financial, insurance, tax or medical advice. ConnectingCrowd is not affiliated with any government agency, insurer or lender. Please do your own research and talk to a licensed professional before making any decision.