
In 30 seconds
- SBA microloans go up to $50,000, and the SBA says the average is about $13,000.
- The maximum repayment term is seven years.
- Interest rates vary by lender but are generally between 8% and 13%, according to the SBA.
- Microloans can't be used to pay existing debts or buy real estate.
In this article
SBA microloans at a glance
- Maximum: $50,000
- Average: about $13,000
- Maximum term: seven years
- Typical rates: generally 8% to 13%
- Not allowed: paying existing debts or buying real estate
From SBA.gov, Microloans.
How the microloan program works
The SBA doesn't lend the money directly. Instead, the SBA says it provides funds to specially designated intermediary lenders, usually nonprofit community organizations. Those lenders then make loans to small businesses.
The SBA is clear that these lenders are in charge of the loan: SBA-approved lenders make all credit decisions and set all terms for your microloan. That means requirements, rates and paperwork can differ from one lender to the next.
| Feature | SBA microloan |
|---|---|
| Loan size | Up to $50,000; average about $13,000 |
| Maximum term | Seven years |
| Interest rate | Generally 8% to 13%, depending on the lender |
| Who decides | The intermediary lender |
| Can't be used for | Paying existing debts or buying real estate |
Source: SBA.gov, Microloans.
Microloan vs. personal loan for your business
Many small business owners borrow personally because it seems faster. But there are real differences to consider:
| SBA microloan | Personal loan | |
|---|---|---|
| Designed for | Small businesses | Personal expenses (some lenders allow business use) |
| Loan size | Up to $50,000 | Varies by lender |
| Who it's in the name of | Usually the business, with lender requirements | You personally |
| Rates | Generally 8% to 13% (SBA) | Depend on your credit and the lender |
| Extra help | Many intermediaries offer business support | Usually none |
General comparison. Terms vary by lender.
A personal loan puts the debt in your name, so it can affect your personal credit if the business struggles. If you do use a personal loan for business, keep records of how the money was spent. That can matter at tax time, since business interest may be treated differently from personal interest.
What you can and can't use a microloan for
The SBA's rules are specific about one thing: proceeds from an SBA microloan cannot be used to pay existing debts or to purchase real estate. That means you can't use a microloan to refinance business credit cards or buy a building.
Within those limits, lenders decide what's allowed. Ask your lender how you plan to use the money, such as buying equipment, inventory or supplies, or covering startup costs, and get its answer in writing.
Lenders want to know how you'll use the money and how you'll repay it. A simple business plan and budget can make your application stronger.
An example
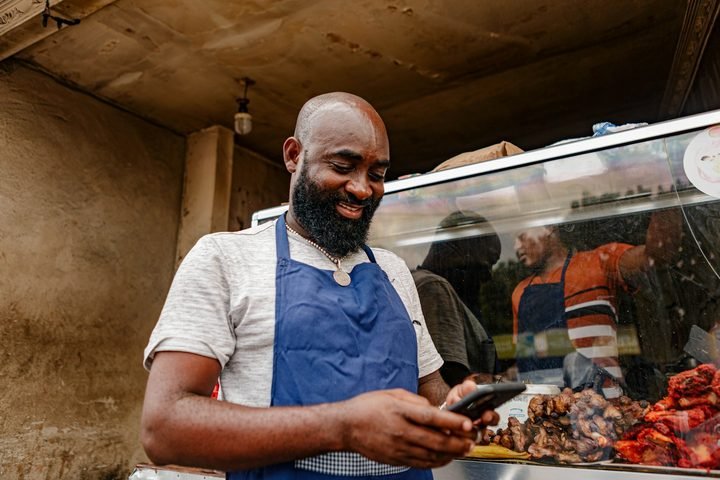
Andrea's food truck
Andrea wants to buy kitchen equipment for a food truck. A personal loan would put the debt in her name, and her credit is still building.
She finds an SBA microloan intermediary in her city. It asks for a business plan, a budget and an explanation of how she'll use the money.
She's approved for a microloan to buy equipment, with a term of several years. The lender also connects her with free small business advising.
Her loan payments fit her projected sales, and the debt is tied to her business plan rather than her personal spending.
Illustrative example. Names are made up. Terms are set by each lender.
How to apply
- Find an intermediary lender Use SBA.gov to find microloan lenders in your area.
- Prepare your plan Have a business plan, budget and a clear use for the money.
- Ask about requirements Each lender sets its own credit, collateral and paperwork rules.
- Compare costs Ask for the interest rate, fees and total cost of the loan.
- Read the terms Make sure the payment schedule fits your expected cash flow.
If a microloan isn't a fit, compare it with other options, including personal loans, but weigh the risk of putting business debt in your own name.
Other ways small businesses borrow
| Option | Things to consider |
|---|---|
| SBA microloan | Up to $50,000; terms up to seven years; rates generally 8% to 13% |
| Personal loan | In your name; can affect your personal credit; rates depend on your credit |
| Business credit card | Revolving credit; can be costly if you carry a balance |
| Personal savings or family | No interest to a lender, but your own money is at risk |
Microloan figures from SBA.gov. Other options vary by lender.
Whatever you choose, borrow only what your business plan supports. A loan payment that depends on optimistic sales can quickly become a personal financial problem.
Keep business and personal money separate
Opening a separate business bank account makes it easier to track loan spending, show lenders how your business is doing and keep records for taxes. If you used a personal loan for business costs, records showing exactly what the money paid for are especially important, since business interest may be treated differently from personal interest at tax time.
- ✓ Open a business account for loan proceeds and business expenses.
- ✓ Keep receipts for every purchase made with borrowed money.
- ✓ Track payments so you never miss a due date.
Common mistakes to avoid
- ✓ Planning to refinance debt with a microloan. The SBA says proceeds can't be used to pay existing debts.
- ✓ Borrowing to buy property. Microloans can't be used to purchase real estate.
- ✓ Skipping the comparison. Rates and terms vary between intermediary lenders.
Questions to ask a microloan lender
Before you apply, ask the lender what interest rate and fees it charges, how long the term will be, whether it requires collateral or a personal guarantee, how long a decision takes, and whether it offers business training or advising. The SBA says each intermediary lender sets its own terms, so compare more than one if you can.
Frequently asked questions
What is the average SBA microloan?
The SBA says the average microloan is about $13,000, though loans can go up to $50,000.
How do I find an SBA microloan lender?
Start at SBA.gov, which explains the microloan program and how to find intermediary lenders in your area.
Do SBA microloans require collateral?
It depends on the lender. The SBA says intermediary lenders make all credit decisions and set all terms, so ask each lender.
How much can I borrow with an SBA microloan?
Up to $50,000. The SBA says the average microloan is about $13,000.
What is the interest rate on an SBA microloan?
The SBA says rates vary by lender but are generally between 8% and 13%.
How long can an SBA microloan last?
The maximum repayment term is seven years.
Can I use an SBA microloan to pay off debt?
No. The SBA says microloan proceeds can't be used to pay existing debts or buy real estate.
Who makes SBA microloans?
Intermediary lenders funded by the SBA. They make all credit decisions and set the terms.
Is a personal loan or a microloan better for a small business?
It depends. A microloan is designed for businesses, while a personal loan puts the debt in your name. Compare costs and risks.
Ready to compare loan options?
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare personal loan options
SponsoredRelated guides
See all personal loans guides Is personal loan interest tax deductible? The IRS rule and its exceptions
 How to get a personal loan: a 7-step plan from first check to funding
 Personal line of credit: flexible borrowing you can tap as needed, and when it beats a loan
 How loan amortization works: where each payment goes and how to pay less interest
 How to check if a lender is licensed in your state, step by step
 Earned wage access apps: how paycheck advances work and what they really cost
See loan options in your state
Loan options vary by state and lender. Enter your ZIP code to compare options. Looking is free.
Compare loan options for your situation
SponsoredSources
Disclaimer: This article is for general information only and is based on publicly available sources, which may be incomplete, outdated or incorrect. It is not legal, financial, insurance, tax or medical advice. ConnectingCrowd is not affiliated with any government agency, insurer or lender. Please do your own research and talk to a licensed professional before making any decision.