
In 30 seconds
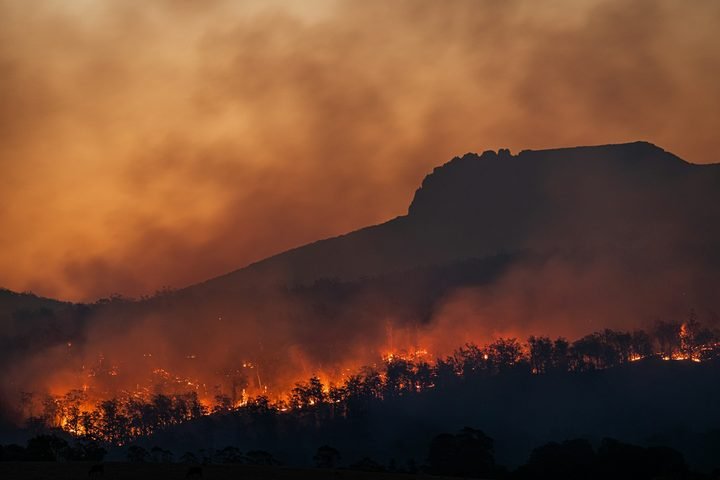
- Fire is a covered peril on standard homeowners policies. Wildfire damage is generally covered up to your limits.
- Replacement cost coverage pays to rebuild with materials of similar kind and quality. Actual cash value subtracts for age and wear, and often doesn't pay enough to fully rebuild.
- In California, you get no less than 24 months to collect additional living expenses after a declared catastrophe, even if your policy says otherwise.
- California requires insurers to give discounts to property owners who reduce wildfire risk through specific mitigation steps.
- If you can't find coverage, California's FAIR Plan is a safety net, but it offers limited coverage.
In this article
Wildfire coverage at a glance
- Fire: a standard covered peril
- Rebuilding: depends on your dwelling limit and replacement cost coverage
- Living expenses: covered under additional living expenses (loss of use)
- California ALE: at least 24 months after a declared catastrophe
- Building code upgrades: may need ordinance or law coverage
Sources: NAIC, A consumer's guide to home insurance; California Department of Insurance.
Does homeowners insurance cover wildfire damage?
Yes, in general. The NAIC's consumer guide to home insurance lists fire as an example of a covered peril. A standard homeowners policy covers your house, other structures, your belongings and your extra living costs if a fire forces you out, up to the limits on your policy.
| Part of your policy | What it pays for after a wildfire |
|---|---|
| Dwelling | Repairing or rebuilding your home |
| Other structures | Detached garages, sheds and fences |
| Personal property | Your belongings, often 50% of the dwelling limit |
| Loss of use / additional living expenses | Temporary rent, extra mileage and other added costs |
| Ordinance or law (if you have it) | Extra cost to rebuild to current building codes |
Source: NAIC, A consumer's guide to home insurance. Limits and percentages vary by policy.
Will your policy be enough to rebuild?
The biggest wildfire risk to your finances is being underinsured. The NAIC explains that replacement cost is the cost to rebuild your home or repair damage using materials of similar kind and quality, while actual cash value considers age and wear and tear and often doesn't pay enough to fully repair or replace the damage.
The NAIC also describes guaranteed replacement cost coverage, which pays to completely rebuild your home, and an ordinance or law endorsement, which pays the extra expense of rebuilding to current building codes. After a large fire, building costs can rise quickly, so these options matter.
Ask your insurer whether your dwelling limit reflects today's rebuilding costs, and whether you have extended replacement cost and building code upgrade coverage.
Your rights after a wildfire (California)
The California Department of Insurance publishes top tips for wildfire claimants. Several reflect California law, and they're useful questions to ask in any state:
- ✓ Get a complete copy of your policy. In California, your insurer must provide it free within 30 days of your request.
- ✓ Your time to collect additional living expenses after a declared catastrophe is no less than 24 months, even if your policy says otherwise. Extensions of up to 12 more months should be granted for delays beyond your control.
- ✓ Additional living expenses don't pay your mortgage or costs you'd normally have, but do cover things like temporary rent and extra mileage.
- ✓ Get at least one licensed contractor's estimate to rebuild. Insurer estimates may miss local conditions and higher post-disaster prices.
- ✓ You can rebuild at another location and keep your full replacement cost benefits, and use the contractor of your choosing.
- ✓ Keep a claim diary of every conversation with your insurer or adjuster.
The department's hotline is 800-927-4357. If you live in another state, your own insurance department can tell you which rules apply.
Public adjusters and contractors after a fire
After a disaster, you'll hear from contractors, lawyers and public adjusters. California's advice is not to rush into any decision. It notes that public adjusters typically charge a percentage of the claim settlement, shouldn't charge a fee on payments you received before signing with them, and that after a declared disaster you may cancel a public adjuster contract within five calendar days. Our guides to public adjusters and avoiding contractor fraud explain more.
Mitigation can earn discounts
Reducing wildfire risk protects your home and can lower your premium. The California Department of Insurance says regulations require insurance companies to give wildfire safety discounts to property owners who reduce risk through specific mitigation efforts, under the state's Safer from Wildfires framework. It explains the goal plainly: safer communities help keep insurance affordable and available.
Ask your insurer which mitigation steps it recognizes and what proof it needs, such as photos or an inspection.
If you can't find coverage
In high-risk areas, some homeowners struggle to find a policy. California's FAIR Plan was created as a safety net for people who can't find other coverage. The department says it currently offers only limited coverage for fire and smoke damage, so you'd need a separate policy for water damage, liability and other risks. Our California FAIR Plan guide explains how that works. Other states have their own FAIR plans and insurers of last resort.
Get ready before a fire
- Make a home inventory The NAIC suggests a household inventory with photos and receipts, stored somewhere outside your home.
- Review your limits Check your dwelling, personal property and living expense limits.
- Ask about upgrades Extended replacement cost, guaranteed replacement cost and ordinance or law coverage.
- Reduce your risk Ask your insurer which mitigation steps qualify for discounts.
- Keep documents safe Store your policy and declarations page in the cloud or with someone outside your area.
Know your policy before you need it
California's wildfire guidance warns not to assume you have inadequate coverage based on general information you hear, and to evaluate your own limits case by case. The best time to do that is now. Pull out your declarations page and note your dwelling limit, personal property limit and loss of use limit.
The bottom line
Wildfire damage is generally covered by homeowners insurance, but how well you recover depends on your limits and whether you have replacement cost and building code coverage. Review your policy before fire season, make a home inventory, reduce your risk, and know your rights if you ever need to file a claim.
Frequently asked questions
Does homeowners insurance cover wildfires?
Generally yes. Fire is a standard covered peril, so wildfire damage is covered up to your policy limits.
How long can I get living expenses after a wildfire in California?
No less than 24 months after a declared catastrophe, even if your policy says otherwise, with extensions of up to 12 more months for delays beyond your control.
What is the difference between replacement cost and actual cash value?
Replacement cost pays to rebuild with similar materials. Actual cash value subtracts for age and wear and often doesn't pay enough to fully rebuild.
Can I get a discount for wildfire mitigation?
In California, regulations require insurers to give discounts to property owners who reduce wildfire risk through specific mitigation steps.
What if no insurer will cover my home?
California's FAIR Plan is a safety net, but it offers limited fire and smoke coverage, so you may need a separate policy for other risks.
Review your home insurance coverage
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare home insurance options
SponsoredRelated guides
See all home insurance guides The California FAIR Plan: coverage when regular insurers say no
 Replacement cost vs actual cash value: the difference that decides your claim check
 Additional living expenses coverage: how your policy helps when you must move out
 Does homeowners insurance cover stolen packages? What to do when a porch pirate strikes
 Space heater fires and home insurance: what's covered, and the safety rules that prevent them
 Does homeowners insurance cover dog bites? What's covered, and when breed matters
See home insurance options in your state
Coverage and prices vary by state and insurer. Enter your ZIP code to compare options. Looking is free.
Compare home insurance for your situation
SponsoredSources
Disclaimer: This article is for general information only and is based on publicly available sources, which may be incomplete, outdated or incorrect. It is not legal, financial, insurance, tax or medical advice. ConnectingCrowd is not affiliated with any government agency, insurer or lender. Please do your own research and talk to a licensed professional before making any decision.