
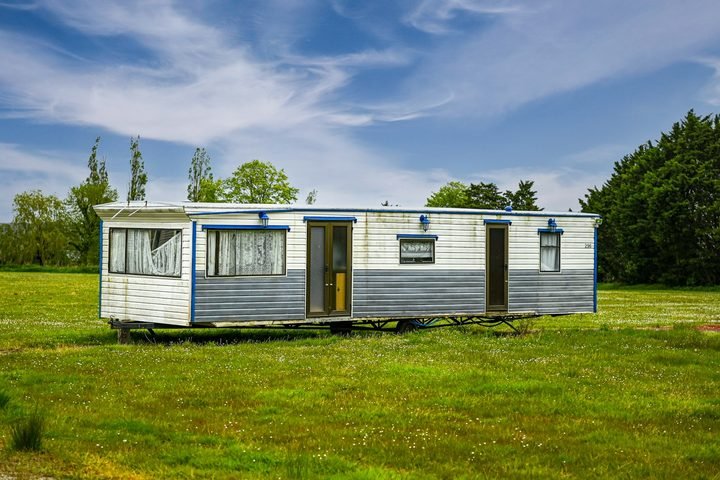
In 30 seconds
- Mobile home insurance can cover the home, your belongings, liability and living costs after a covered loss, similar to a homeowners policy.
- Ask whether a policy pays replacement cost or actual cash value. Actual cash value subtracts depreciation, which can leave a big gap on an older home.
- Flood damage needs a separate flood policy. The Texas Department of Insurance says many Gulf Coast homes also need a separate windstorm policy.
- TDI suggests asking about discounts and working with an independent agent who can check several insurers.
- In Texas, if two insurers have turned you down, you may be able to get coverage through the Texas FAIR Plan.
In this article
Mobile home insurance at a glance
- Covers: home, belongings, liability, living costs
- Ask: replacement cost or actual cash value?
- Flood: separate policy
- Wind on the Texas coast: often separate
- Turned down twice in Texas: Texas FAIR Plan
Sources: Texas Department of Insurance; NAIC.
What a mobile home policy usually covers
A policy for a manufactured or mobile home is built much like a homeowners policy. The NAIC's consumer guide to home insurance describes the main parts of home coverage, and mobile home policies usually include similar pieces:
| Coverage | What it pays for |
|---|---|
| The home itself | Repairing or replacing the home after a covered loss, such as fire |
| Other structures | Sheds, carports or decks on the property |
| Personal property | Furniture, clothing and other belongings |
| Loss of use | Extra living costs if you can't live in the home during repairs |
| Liability | Injuries to others or damage you cause to their property |
Coverage varies by policy. Read yours for exact terms.
The NAIC guide says personal property coverage is often set at about 50% of the dwelling amount and loss-of-use coverage at about 20% on a typical homeowners policy. Mobile home policies may use different amounts, so check your declarations page.
Replacement cost vs actual cash value
This is the most important question to ask. The NAIC's shopping tool explains that actual cash value coverage pays to repair or replace the home minus a deduction for age and wear and tear, called depreciation. Replacement cost coverage pays to repair or replace it with materials of like kind and quality, without that deduction.
Why it matters for an older home
Rosa's 20-year-old manufactured home is destroyed by fire.
Replacing it with a similar new home would cost $90,000.
With actual cash value coverage, depreciation is subtracted, so her payment could be far less than $90,000.
With replacement cost coverage, up to her limit, she gets closer to what it costs to replace the home.
Illustrative example. Numbers are made up.
Illustrative example. Names and numbers are made up to show how it works.
Replacement cost coverage usually costs more, but it can make the difference between rebuilding and starting over. Our guide to replacement cost vs actual cash value explains the trade-off.
Questions the Texas Department of Insurance suggests asking
The Texas Department of Insurance's tips for insuring a manufactured home suggest asking insurers about:
- ✓ How much coverage you need for the home and your belongings.
- ✓ Whether the policy pays replacement cost or actual cash value.
- ✓ Discounts you may qualify for.
- ✓ Whether flood damage is covered, and if not, how to get flood insurance.
- ✓ Whether windstorm damage is covered where you live.
TDI also suggests working with an independent agent, who can check prices and coverage with several insurers.
Flood and windstorm: the two big gaps
Regular policies generally don't cover flooding. The Texas Department of Insurance says flood coverage is a separate policy, and many people along the Gulf Coast also need a separate windstorm policy. If you live near water or in a storm-prone area, ask about both before hurricane season, not after a storm is on the way. Our flood insurance guide explains how flood policies work.
Flood policies often have a waiting period before coverage starts. Buy it well before you need it.
If insurers turn you down
Some manufactured homes can be harder to insure. In Texas, the Texas Department of Insurance says that if two insurers have turned you down, you may be able to buy coverage from the Texas FAIR Plan, an insurer of last resort. You can reach the Texas FAIR Plan at 800-979-6440. Many other states have their own FAIR plans or similar programs. California's is covered in our California FAIR Plan guide.
If you have questions about insurance in Texas, the Texas Department of Insurance's help line is 800-252-3439. In other states, contact your state insurance department.
Make a home inventory
The NAIC recommends keeping an inventory of your belongings, with photos or video, and storing it somewhere other than your home. It makes a claim faster and helps you choose the right amount of personal property coverage. Our home inventory guide shows how to build one in an afternoon.
After damage: protect the home
The NAIC's home insurance guide says policyholders are expected to protect their property from further damage after a loss, such as covering a broken window or a damaged roof. Keep receipts for the materials. Insurers may deny coverage for damage that gets worse because nothing was done. Then report the claim promptly. See our guide on how to file a home insurance claim.
Shopping checklist
- Know your home's value Get an estimate of what it would cost to replace it.
- Ask for replacement cost quotes Compare them with actual cash value quotes.
- Check flood and wind Ask what is excluded and what separate policies you need.
- Compare at least three insurers An independent agent can help, as TDI suggests.
- Ask about discounts Such as for safety features or bundling.
If you rent your lot
Many manufactured homes sit on rented lots in a community. If that's you, your policy covers your home and belongings, not the land or the community's shared buildings. Ask the community what insurance it requires residents to carry, and read your lease. If the home is financed, your lender may also require certain coverage and may need to be listed on the policy.
If you disagree with the claim amount
The NAIC's home insurance guide explains that many policies have an appraisal clause. It's a way to settle a disagreement over the amount of a loss without going to court. Read your policy to see whether it has this clause and how it works. You can also contact your state insurance department, or in Texas, the TDI help line at 800-252-3439.
The bottom line
Mobile home insurance covers the same basics as homeowners insurance, but older homes are often insured for actual cash value, and flood and wind can be separate. Ask about replacement cost, close the flood and wind gaps, compare several insurers, and know your state's backup options if you're turned down.
Frequently asked questions
Does mobile home insurance cover my belongings?
Usually yes, through personal property coverage, up to the limit on your policy. Make a home inventory so you know how much coverage you need.
Does homeowners insurance cover mobile homes?
Mobile and manufactured homes are often insured with a policy designed for them, which covers similar things: the home, belongings, liability and living costs.
Does mobile home insurance cover floods?
Usually not. The Texas Department of Insurance says flood coverage is a separate policy.
What is the difference between replacement cost and actual cash value?
The NAIC says actual cash value subtracts depreciation, while replacement cost pays to replace with materials of like kind and quality without that deduction.
What if no one will insure my mobile home?
In Texas, if two insurers turn you down, you may qualify for the Texas FAIR Plan. Other states have similar programs.
Should I use an independent agent?
The Texas Department of Insurance suggests it, because an independent agent can compare several insurers for you.
Review your home insurance coverage
Compare options available where you live, or call to talk it through with a licensed agent. Looking is free.
ConnectingCrowd is an information site and is not affiliated with any government agency.
Compare home insurance options
SponsoredRelated guides
See all home insurance guides Replacement cost vs actual cash value: the difference that decides your claim check
 Flood insurance explained: the coverage your homeowners policy leaves out
 How much homeowners insurance do I need? Start with what it costs to rebuild
 Does homeowners insurance cover stolen packages? What to do when a porch pirate strikes
 Space heater fires and home insurance: what's covered, and the safety rules that prevent them
 Does homeowners insurance cover dog bites? What's covered, and when breed matters
See home insurance options in your state
Coverage and prices vary by state and insurer. Enter your ZIP code to compare options. Looking is free.
Compare home insurance for your situation
SponsoredSources
Disclaimer: This article is for general information only and is based on publicly available sources, which may be incomplete, outdated or incorrect. It is not legal, financial, insurance, tax or medical advice. ConnectingCrowd is not affiliated with any government agency, insurer or lender. Please do your own research and talk to a licensed professional before making any decision.